Alright, buckle up! Navigating the winding roads of auto insurance in Massachusetts can feel like a daunting drive through Boston traffic. But fear not—our comprehensive guide is here to steer you clear of confusion and help you find the right coverage at an affordable price.
In this guide, we’re diving deep into everything you need to know about auto insurance costs in Massachusetts. From understanding the essential coverage types and legal requirements to discovering savvy tips for snagging discounts, we’ve got you covered. Let’s hit the road!
Overview of Auto Insurance in Massachusetts
Did you know that Massachusetts boasts some of the most stringent auto insurance requirements in the U.S.? With a unique mix of mandatory coverage and state oversight, understanding what’s needed can save you a ton of headaches.
Whether you’re new to Massachusetts or just need a refresher, it’s crucial to grasp the ins and outs of auto insurance here. The state mandates certain coverage types that every driver must have, and knowing these can make or break your policy.
Basic Requirements for Auto Insurance in Massachusetts
In Massachusetts, every driver must carry a minimum level of auto insurance. This isn’t just a suggestion—it’s the law. The state requires you to have four main types of coverage: Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property.
- Bodily Injury to Others: Protects other people if you’re at fault in an accident.
- Personal Injury Protection (PIP): Covers medical expenses and lost wages for you and your passengers.
- Bodily Injury Caused by an Uninsured Auto: Steps in if the other driver doesn’t have insurance.
- Damage to Someone Else’s Property: Covers repairs or replacements for property you damage.
Legal Minimum Insurance Coverage Limits
The state doesn’t just dictate the type of coverage; it also sets minimum coverage limits. Here’s the deal: you must have at least $20,000 per person and $40,000 per accident for Bodily Injury to Others. For PIP, the minimum is $8,000 per person. Property Damage? You need at least $5,000.
| Coverage Type | Minimum Limit |
|---|---|
| Bodily Injury to Others | $20,000 per person / $40,000 per accident |
| Personal Injury Protection (PIP) | $8,000 per person |
| Bodily Injury Caused by an Uninsured Auto | Same as Bodily Injury to Others |
| Property Damage | $5,000 |
The Role of the Massachusetts Division of Insurance
You might be wondering, “Who’s making sure all this is followed?” That’s where the Massachusetts Division of Insurance comes in. This state agency regulates insurance providers to ensure they adhere to the rules and offer fair rates. They also approve the insurance products offered, so you’re not left high and dry with subpar coverage.
Pro Tip: Always check if your insurer is licensed by the Massachusetts Division of Insurance to avoid any dodgy deals.
By understanding these elements, you’re not just complying with the law—you’re protecting yourself and your assets. So, make sure your policy ticks all these boxes.
Factors Influencing Auto Insurance Costs in Massachusetts
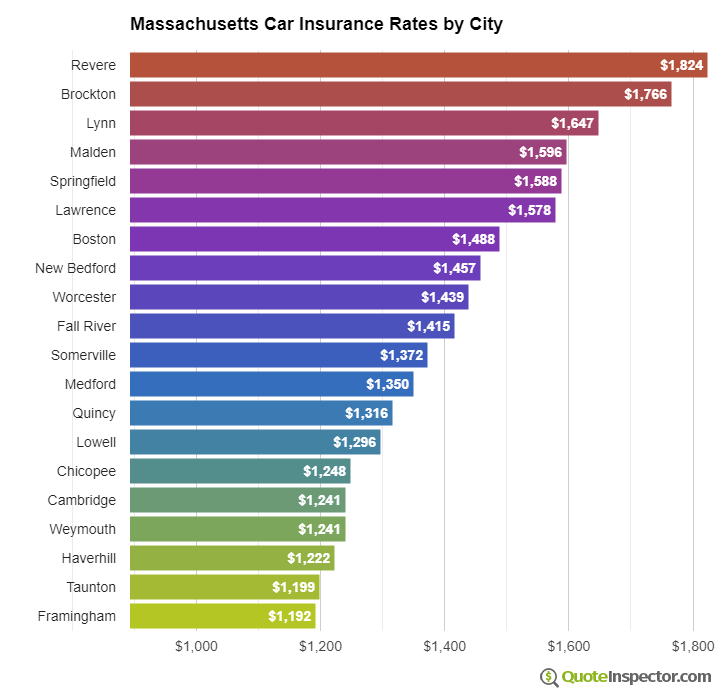
Ever wondered why your auto insurance rate seems mysteriously higher than your buddy’s in another town? You’re not alone. In Massachusetts, several key factors can make or break your auto insurance premium.
The cost isn’t just about the car you drive. It’s about who you are, where you live, and even how old you are. Let’s dive in and break down these factors.
Impact of Location Within Massachusetts
Location, location, location. That’s the mantra not just for real estate, but for auto insurance in Massachusetts too. Your zip code can have a massive impact on your premium. Live in an urban area like Boston? Expect higher rates due to increased traffic and theft risks. But, if you’re in a quieter spot like Worcester, you might catch a break.
Here’s the deal: Insurance companies analyze accident statistics and crime rates in your area to calculate your premium. Moving just a few miles could save you a bunch!
Vehicle Types and Insurance Rates
Think your dream sports car won’t affect your insurance? Think again. Cars with higher repair costs or that are statistically involved in more accidents will inflate your premium. Sedans and family-friendly SUVs often come with lower rates compared to flashy convertibles or luxury vehicles.
Pro Tip: If you’re looking for a new car, consider the insurance cost as part of your budget. It could save you hundreds annually!
Insurance Cost Comparison by Age and Driving History
Age and driving history are critical. Young drivers or those with a few speeding tickets can expect to pay more. But how much more? Let’s look at some numbers.
| Age Group | Clean Record | 1-2 Violations |
|---|---|---|
| 18-24 | $2,500 | $3,300 |
| 25-34 | $1,800 | $2,500 |
| 35-50 | $1,400 | $1,900 |
| 50+ | $1,200 | $1,600 |
As you can see, keeping a clean driving record can drastically cut your insurance costs. It’s not just about age; it’s about how safe you are on the road.
Average Cost of Auto Insurance in Massachusetts
Did you know the average cost of auto insurance in Massachusetts is around $1,300 per year? That’s a bit lower than the national average, which might surprise you if you’ve ever heard horror stories about pricey insurance in the Northeast.
Here’s the deal: Massachusetts benefits from a unique mix of factors like lower accident rates and state regulations that help keep premiums in check. BUT, it’s not all smooth sailing—your location within the state can still drastically affect what you pay.
Comparison with Other States
So, how does Massachusetts stack up against its neighbors? Well, let’s just say you’re in a better position than our friends in New York or New Jersey, where the rates can shoot up past $1,500 a year. Yet, you might pay more than someone in Maine, where the average cost hovers around $900. The difference largely comes down to state laws and population density.
Here’s a table that breaks down average costs by coverage level:
| Coverage Level | Average Cost in MA |
|---|---|
| Minimum Coverage | $500 |
| Full Coverage | $1,300 |
| High Coverage | $1,700 |
Factors Influencing Insurance Trends
So what’s driving these numbers? One word: trends. Massachusetts is experiencing a rise in urbanization, leading to more traffic congestion and potentially more accidents. On the flip side, advancements in vehicle safety technologies are helping to keep serious incidents down, which could stabilize rates over time.
Pro Tip: Keep an eye on new technologies like telematics, which track your driving habits. Safe drivers can nab some sweet discounts!
There’s no denying that auto insurance costs can feel like an unpredictable beast. But by understanding these elements, you can better strategize on how to manage your rates.
Discounts and Savings on Auto Insurance
Did you know that there are tons of ways to save on auto insurance in Massachusetts? You might be leaving money on the table without even realizing it. Let’s dive into the discounts and savings you can snag.
Auto insurance companies often offer a variety of discounts to help you cut costs. BUT, many drivers don’t take full advantage because they don’t know what’s available or how to qualify. Here is the deal: by understanding and leveraging these discounts, you can substantially lower your premiums.
Common Discounts Available to Massachusetts Drivers
Here’s a rundown of the most common discounts you can find:
- Good Driver Discount: If you’ve maintained a clean driving record, you’re in luck. This discount rewards you for being safe on the road.
- Multi-Policy Discount: Bundling your auto insurance with home or renters insurance can save you a bundle.
- Low Mileage Discount: Drive less, pay less. Simple as that.
- Student Discount: Got a student in the family who excels in school? Their good grades could translate into insurance savings.
- Safety Features Discount: Cars with the latest safety features can earn you a discount. Think anti-lock brakes or airbags.
Qualifying for Auto Insurance Discounts in Massachusetts
So, how do you make these discounts work for you? It’s easier than you think:
- Regularly review your policy and ask your insurer about potential discounts.
- Maintain a clean driving record to qualify for safe driver discounts.
- Consider defensive driving courses; they often lead to insurance savings.
- Keep your car’s mileage low by using alternative transportation when possible.
Pro Tip: Always ask your insurer if there are any new discounts available or if you qualify based on recent policy changes.
How Bundling Policies Can Lower Premiums
Bundling is a straightforward way to save. By combining your auto insurance with other policies, you can unlock significant savings.
| Insurance Type | Potential Discount |
|---|---|
| Auto + Home | Up to 25% |
| Auto + Renters | Up to 15% |
See? Bundling equals big savings. It’s a no-brainer if you have multiple insurance needs.
Example Scenario: Safe Driving Discounts
Let’s say you’re a Massachusetts driver with a spotless record. You’ve never had an accident or traffic violation.
This qualifies you for a safe driver discount, potentially saving you 15-20% on your premium. Over a year, that could be hundreds of dollars back in your pocket. All from driving safely!
Finding the Right Auto Insurance Provider in Massachusetts
Choosing the right auto insurance provider can feel like finding a needle in a haystack. But with the right strategy, you can secure a policy that suits your needs and budget.
Here is the deal: Not all insurance providers are created equal. You need to effectively compare companies to ensure you’re getting the best coverage and customer service.
Comparing Auto Insurance Providers
Start by listing a few providers you’re interested in. Compare them based on customer reviews, financial stability, and the coverage options they offer. A little research can go a long way.
- Customer Reviews: Head over to sites like Yelp and the Better Business Bureau to see what real customers are saying.
- Financial Stability: Check ratings from companies like A.M. Best to ensure the insurer can pay claims.
- Coverage Options: Make sure each provider offers the types of coverage you need.
Evaluating Customer Service and Claim Response
You don’t want to be stuck on hold when you need help. So, evaluating customer service is crucial. Look for insurers with strong reputations for handling claims efficiently.
- Call the company and ask a few questions to test their responsiveness.
- Check online for average claim response times.
- Read testimonials about other customers’ claim experiences.
Understanding Policy Terms and Conditions
Insurance jargon can be confusing. But understanding your policy’s terms and conditions is non-negotiable. Always read the fine print.
Pro Tip: If you don’t understand something, ask. Insurance agents are there to help you.
Look out for exclusions, deductibles, and the process for filing claims. This will avoid surprises down the road.
Using Online Tools for Quotes
Online tools can be lifesavers when comparing auto insurance quotes. Comparison websites allow you to see multiple quotes in one place.
- Enter the same details on each site to get accurate comparisons.
- Consider using an insurance broker who can compare quotes for you.
- Remember: cheapest doesn’t always mean best. Balance price with coverage.
Steps to File an Auto Insurance Claim in Massachusetts
Auto accidents can be overwhelming. But filing an auto insurance claim in Massachusetts doesn’t have to be. You’ve just had an accident, and your mind is racing with a million thoughts.
Here’s the deal: knowing the exact steps to take can save you a ton of stress and possibly some cash.
Step-by-Step Process for Filing a Claim
Step #1: Document the Accident Scene. Immediately after an accident, collect as much information as possible. Take photos of the scene, the vehicles involved, and any visible damages. Get the names and contact information of all drivers, passengers, and witnesses.
Step #2: Exchange Insurance Information. Make sure to swap insurance details with the other driver. This includes the insurance company name, policy number, and contact information.
Step #3: Contact Your Insurance Provider. As soon as it’s safe, call your insurance company to start the claims process. They’ll guide you through the next steps and let you know what documents you’ll need.
Step #4: Fill Out Necessary Paperwork. Your insurer might have specific forms for you to complete. This is a crucial step, so don’t skip it!
Step #5: Cooperate with the Insurance Adjuster. An adjuster will assess the damage and determine the payout. Be honest and provide all requested information promptly.
Template for Documenting Accident Details
Having a ready-made template can make your life easier. Here’s a simple format you can use:
- Date and time of the accident
- Location of the accident
- Names and contact details of everyone involved, including witnesses
- Insurance information of all drivers
- Description of the accident scene
- Photos of the accident scene and vehicle damage
Pro Tip: Keep a printed copy of this template in your glove compartment for quick access!
Typical Timeline and What to Expect
Filing a claim can feel like a maze. Typically, you’ll hear back from your insurer within a few days. They might send an adjuster to inspect the damage.
The whole process varies but expect it to take anywhere from a week to a month. Patience is key, but don’t hesitate to follow up if things seem stalled.
Role of Adjusters in Massachusetts
Adjusters are your key contacts during a claim. They evaluate the damage, determine who’s at fault, and calculate the claim amount.
In Massachusetts, adjusters are required to work quickly and fairly. They’ll use photos, repair estimates, and sometimes even witness statements.
Pro Tip: Stay in touch with your adjuster and provide any requested information ASAP to speed up the process!
Final Summary
So there you have it—a full breakdown of how much auto insurance in Massachusetts truly costs and how you can secure the best deal. Armed with this knowledge, you’re ready to navigate the insurance landscape with confidence. Remember, a little research goes a long way in keeping your premiums in check, so stay informed and drive safely!
Q&A
What factors influence auto insurance costs in Massachusetts?
Several factors, including your location, driving history, vehicle type, and age, play a crucial role in determining your insurance premiums in Massachusetts.
How does location affect insurance premiums in Massachusetts?
Urban areas like Boston tend to have higher premiums due to increased traffic and accident risks, while rural areas might offer lower rates.
Are there discounts available for Massachusetts drivers?
Yes, many providers offer discounts for safe driving, bundling policies, using anti-theft devices, and more. Always ask your insurer about available discounts.
What is the average cost of auto insurance in Massachusetts?
While rates can vary, the average annual premium in Massachusetts is typically higher compared to the national average, reflecting the state’s unique risk factors.
How can I file an auto insurance claim in Massachusetts?
Start by documenting the accident details, contact your insurer promptly, and follow their instructions on submitting necessary information for a claim.
